All Categories
Featured
Top Foreign Investment Trends within the Middle East Market
Optimizing Investment Strategies for Next-Gen GCC Economy

Will Middle East Markets Grow in 2026?
Table of Contents
Looking ahead, positive forecasts for a healthy IPO pipeline across the Gulf over the next 12-18 months are evident. This optimism is buoyed by alleviating geopolitical tensions, which have actually formerly affected market confidence. Even normally quieter markets are revealing indications of activity, exemplified by Kuwait's anticipation of an uncommon convenience-store IPO.
Overall, as local markets continue to progress, they reflect the more comprehensive financial and geopolitical narratives at play, providing both obstacles and opportunities for investors engaging with the Middle East.
Top Foreign Investment Prospects in the GCCis for Stock/ Commodity/ Currency/ Forex/ Crypto Market Information functions is not a Financial Consultant/ Influencer and does not supply any trading or financial investment abilities/ ideas/ recommendations through its site/ straight/ social media or through any other channel.Disclaimer/ Disclosure and Privacy Policy/ Terms and conditions are relevant to all users/ members of this site. The chain impacts of rising stress in the Middle East arising from the US and Israeli attacks on Iran and Iran's retaliation have put pressure on the global economy while increasing threats as shown in the stock market performance, monetary policies, and risk premiums of Gulf nations. Stress in the Middle East stayed high on the 20th day, following US and Israeli attacks on Iran and Iranian retaliation.
Reviewing Industrial Success across the Middle East
With brand-new attacks, optimism that the area's tensions would be solved in a short amount of time faded, leaving questions about the possible long-term impacts of the disputes on economies. Iran's retaliation, targeting Gulf countries and tactical facilities, has a direct effect on market characteristics. Serious changes took place in the markets of Gulf nations with the increasing threat perception, while sharp increases stuck out in country risk premiums.
The nation's danger premium increased by approximately 140 basis points to 392. Bahrain's risk premium increased by 84 basis points to 297, while Qatar's threat premium moved up by 13 basis points to 45 in the exact same period.
Saudi Arabia's threat premium come by approximately two basis points to 80.4 in this process. Analysts stated Saudi Arabia experienced reasonably less effect from this circumstance thanks to its strong forex incomes. Stock exchange in the Gulf followed a combined pattern, while the UAE stock market ended up being the one that fell the most because the beginning of the disputes that started with the US and Israeli attacks on Iran and infected other countries in the region.
Shares of petrochemical and energy companies in the region, following a mostly favorable trend in parallel with the increase in oil rates, slowed the decrease in the indices. Offering pressure continued to be reliable in the markets in the UAE, Bahrain, Qatar, and Kuwait, where intense airstrikes happened. Concerns about the country's security prompted a drop in genuine estate and investment firm shares on the UAE stock exchange.
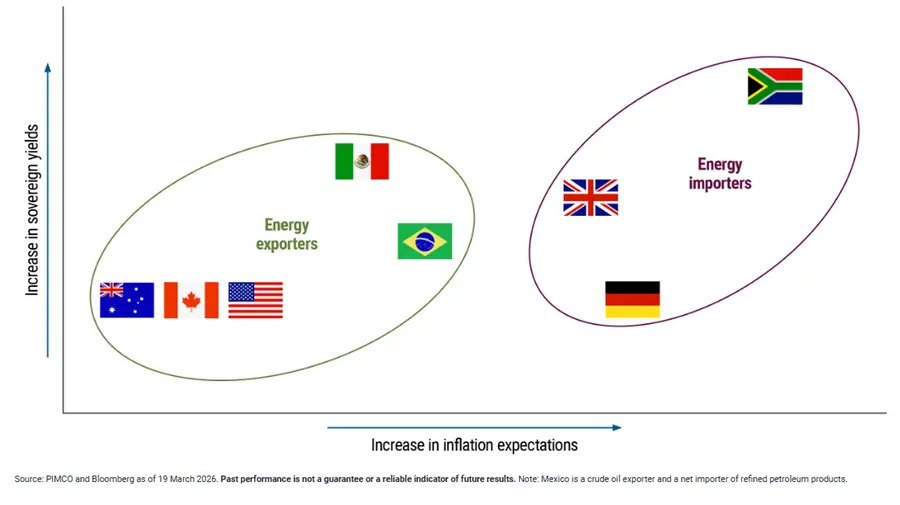
However, airstrikes on energy centers and lines, which intensified following market closures, were not yet priced into local markets. Targeting some oil facilities in the disputes and slowing down maritime traffic in the Strait of Hormuz, which has vital significance for oil shipments, increased energy expenses and fueled international inflation risks upwards.

Why Regional Industrial Diversification Drives 2026 Growth
The Central Bank of the UAE (CBUAE) and the Central Bank of Kuwait (CBK) revealed that their banking systems remained durable. The CBUAE authorized the "Financial Institutions Strength Plan," which is supported by the main bank's one trillion dirhams ($ 270 billion) asset and intends to strengthen the banking sector's stability in the face of exceptional conditions in global and local markets.
The five primary pillars of the plan aim to increase banks' access to monetary liquidity and flexibility to support the UAE economy. Managing forex reserves exceeding one trillion dirhams ($ 270 billion) and a financial base protection ratio of 119%, the bank verified the strong principles of the UAE's 5.4 trillion dirhams ($ 1.47 trillion) banking sector.
A statement from the Reserve bank emphasized that regional banks continued to supply all banking services efficiently and dependably, even under present conditions. The declaration said this success resulted from banks reinforcing their threat management systems, establishing business continuity and emergency situation plans, improving their digital facilities, and carrying out routine exercises replicating possible circumstances in line with the Reserve bank's instructions.
Goldman Sachs, one of the significant US banks, predicted that the economies of Qatar and Kuwait could face a 14% contraction as oil shipments would reduce in a scenario where the Strait of Hormuz stayed closed for two months.

Latest Posts
Top Foreign Investment Trends within the Middle East Market
The 2026 Investment Landscape of the GCC

Optimizing Investment Strategies for Next-Gen GCC Economy