All Categories
Featured
Top Foreign Investment Trends within the Middle East Market
Optimizing Investment Strategies for Next-Gen GCC Economy


The Future Business Climate of the GCC
Table of Contents
Iraq the second-largest producer within the Company of the Petroleum Exporting Countries (OPEC) experienced the largest drop in production, estimated at nearly 70 percent, dropping to about 800,000 barrels per day from 4.3 million barrels prior to the Strait of Hormuz crisis. Egypt's circumstance on the planet Bank report varies from that of some countries in the area that saw sharp contractions; the bank maintained its projection for Egypt's financial development at 4.3%.
Will GCC Industrial Success Outpace Global Averages?"Peace and stability are preconditions for the region's long lasting advancement. With peace and the ideal action, nations can develop the organizations, capabilities and competitive sectors that develop chances for individuals," he added. As for Roberta Gatti, World Bank Group Chief Financial Expert for the Middle East, North Africa, Afghanistan and Pakistan, she stated: "As countries face the heavy toll of the present conflict, it is very important to also not lose sight of the work needed for long-lasting peace and prosperity.".
The current conflict in the Middle East has actually taken a serious and immediate financial toll on countries in the surrounding area. The closure of the Strait of Hormuz and damage of energy and public facilities have interfered with markets, increased financial volatility, and compromised the 2026 development outlook, according to the (MENAAP).
Leaving out Iran, total development in the region is expected to slow from 4.0% in 2025 to 1.8% for 2026. This forecast stands 2.4 portion points below the World Bank Group's January projections. The decrease is focused in Gulf Cooperation Council economies and Iraq, which are greatly impacted by the conflict.
Evaluating GCC Investment Potential for 2026
Risks are tilted to the disadvantage. In the event of a prolonged dispute, the present effect on the area will be compoundedthrough elevated energy and food rates, declining trade, tourism and remittances, increased financial pressures, and displacement. "The present crisis is a stark pointer of the work ahead for the area: not only to weather shocks, but to reconstruct more durable economies with stronger macroeconomic basics, innovate and improve governance, invest in infrastructure, and enhance employment-creating sectors," said.
With peace and the best action, nations can build the institutions, abilities and competitive sectors that create chances for individuals." With this long-lasting vision in mind, the report takes a close look at the region's capacity for commercial policy government actions to increase tactical business activity as a motorist of financial development and task creation.
Federal governments in the area have adopted commercial policy at a high rate in the last decade, typically through sovereign wealth funds and state-owned business, however the outcomes have actually been mixed. The report highlights the critical need for strong organizations and cautious targeting of policies. "As countries face the heavy toll of today dispute, it is essential to also not lose sight of the work needed for lasting peace and success," stated.
Assessing GCC Market Resilience in 2026
The Gulf economies 2026, mostly the ones from the Gulf Cooperation Council (GCC) nations, are getting into 2026 with a fresh drive. The increase in oil production, the development of the Gulf non oil sectors, and the detailed structural reforms are the elements that will make the strong financial development possible.
Here are the significant indicators to observe together with the risks it is better to comprehend before taking any action. The GCC economic outlook is part of this shift, and signals continue to evolve as the area positions for brand-new momentum. Worldwide institutions provide the green light to the Gulf's growth in 2026.
This lines up with a broader GCC growth forecast 2026 that reveals stable enhancement. This healing is an outcome of both the resurgence of hydrocarbon activities and the development of Gulf non oil sectors. Tourist, logistics, production, and finance have been thriving in the most populated and rich in oil countries of the GCC.
Emerging Stock Trading Trends for 2026
Nevertheless, the growth is various in each case. Some projections suggest that the oil cost drop will lead to the cooling off of the development rate. If incomes decrease, financial policy GCC in some nations will be under a heavy test, therefore investors should be especially attentive to oil price volatility GCC.
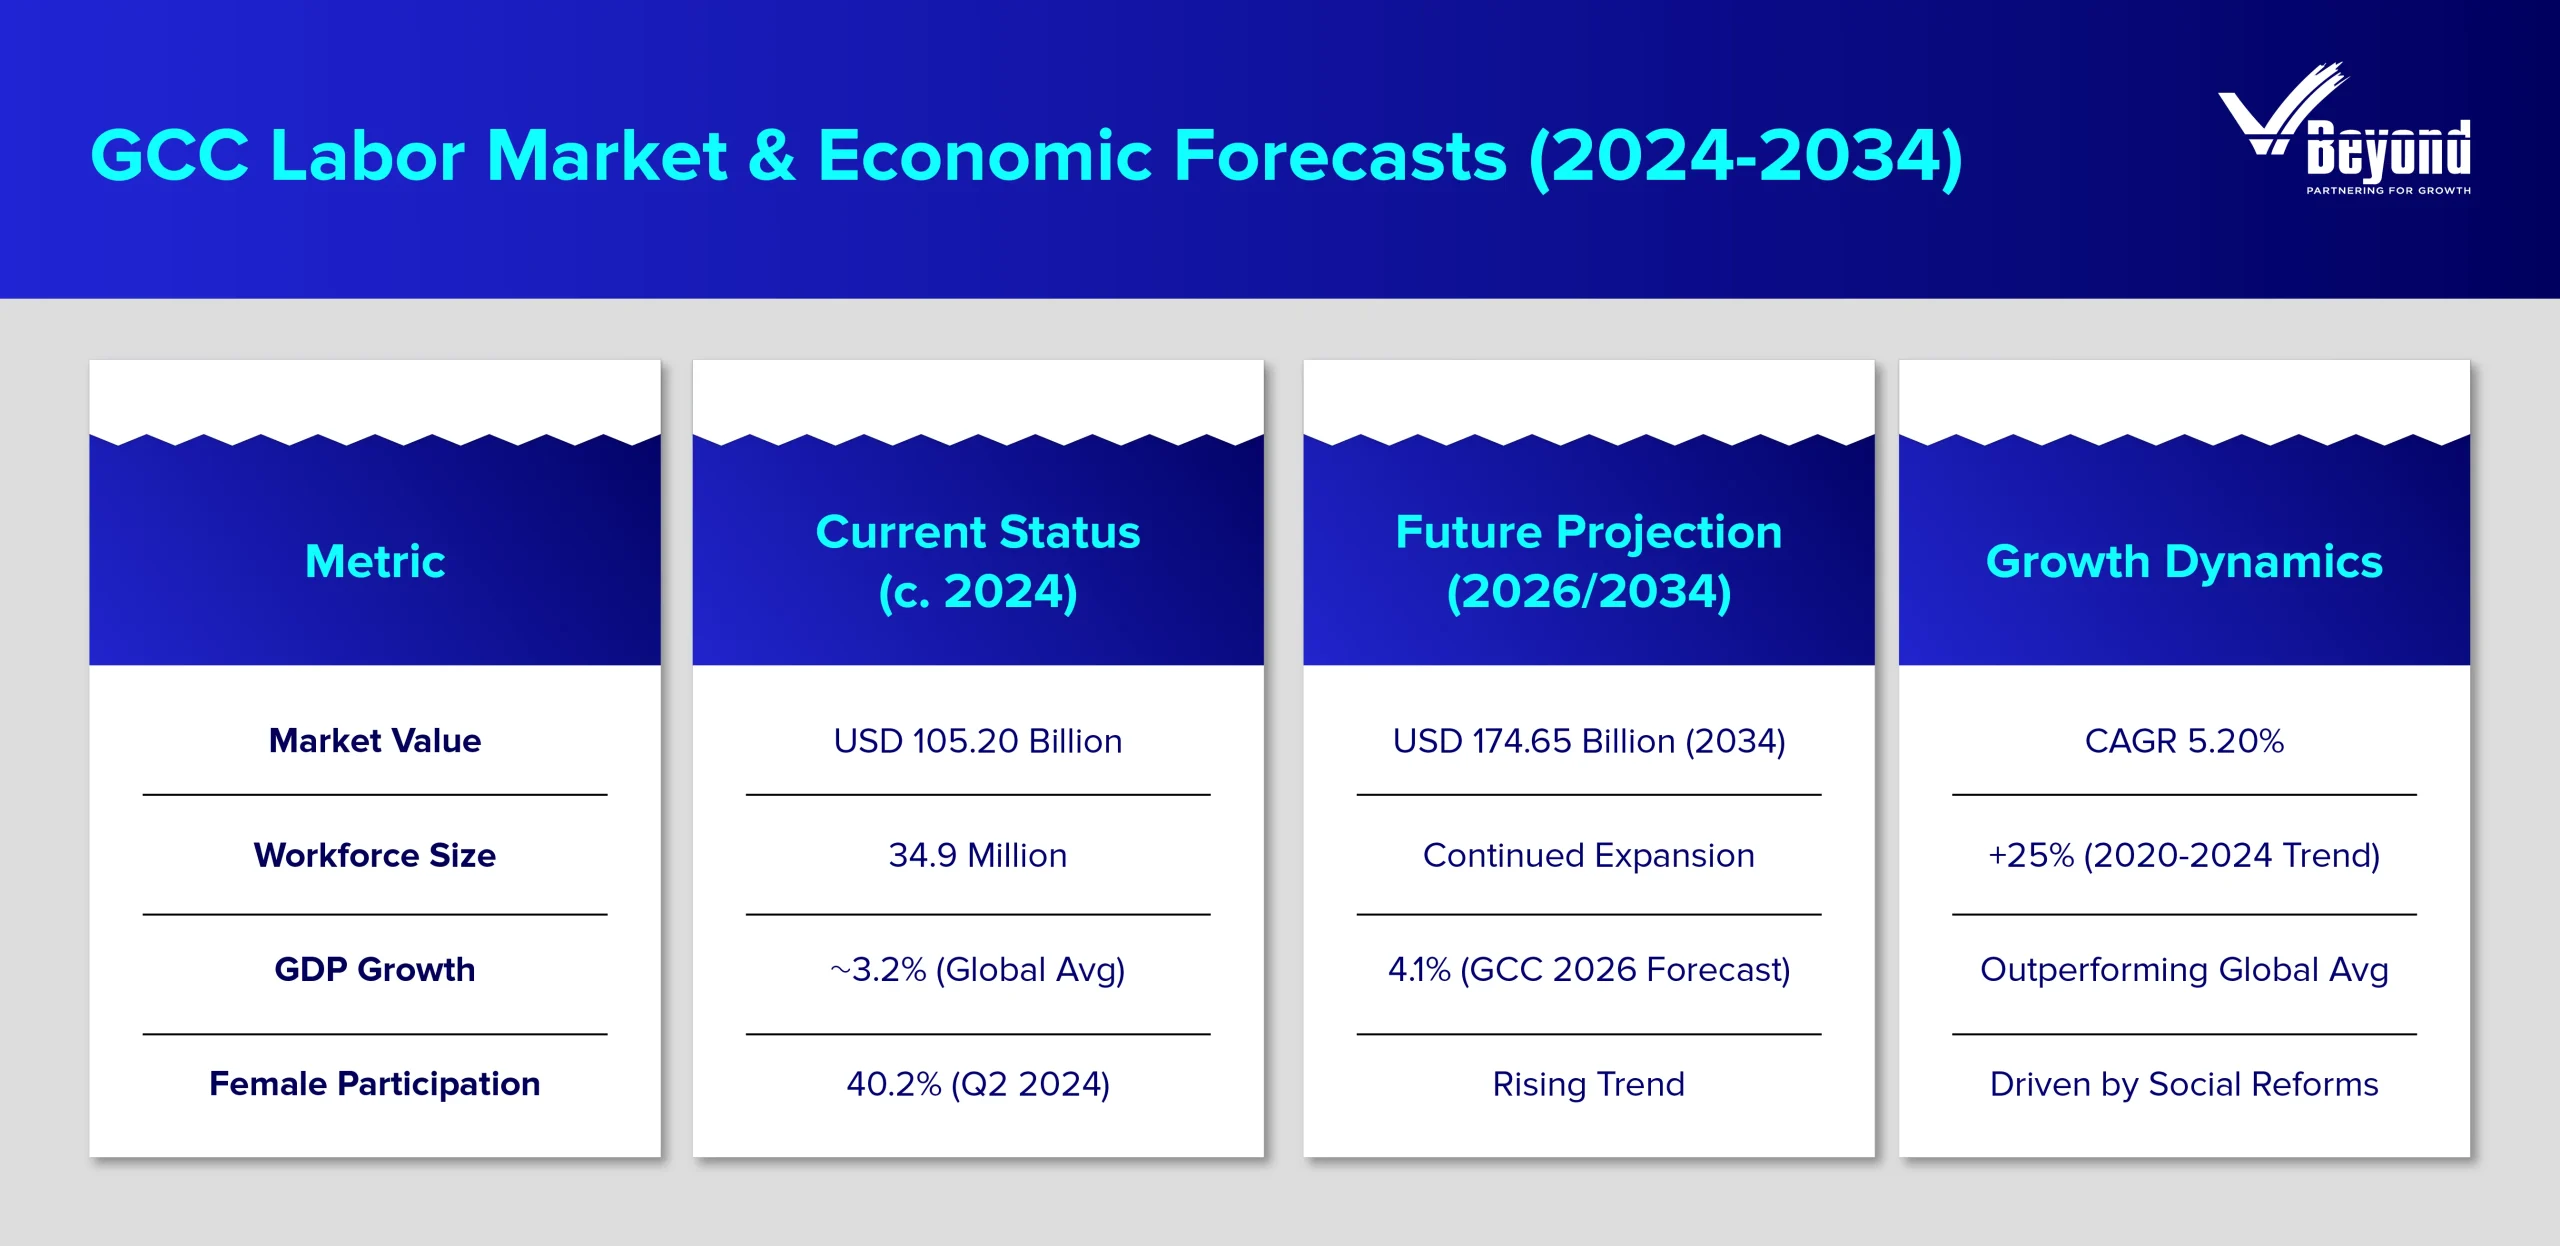
This belongs to bigger GCC diversification efforts that are starting to improve long-term expectations. In the United Arab Emirates, non-oil activities are approximated to be the primary drivers of GDP growth, which would be around 5 to 5.6 percent in 2026. The sectors of tourism, trade, logistics, property, and financial services continue to be the primary engines of the country's economy, reflecting non oil sector growth in GCC countries 2026.

Latest Posts
Top Foreign Investment Trends within the Middle East Market
The 2026 Investment Landscape of the GCC

Optimizing Investment Strategies for Next-Gen GCC Economy