All Categories
Featured
Table of Contents
Iraq the second-largest producer within the Company of the Petroleum Exporting Countries (OPEC) experienced the largest drop in production, estimated at nearly 70 percent, dropping to about 800,000 barrels each day from 4.3 million barrels prior to the Strait of Hormuz crisis. Egypt's circumstance in the World Bank report differs from that of some countries in the region that saw sharp contractions; the bank preserved its forecast for Egypt's economic growth at 4.3%.
Privatization in Kuwait: Balancing State Interests and Market Efficiency"Peace and stability are prerequisites for the region's durable development. With peace and the ideal action, nations can build the institutions, capabilities and competitive sectors that create chances for individuals," he added. As for Roberta Gatti, World Bank Group Chief Economist for the Middle East, North Africa, Afghanistan and Pakistan, she said: "As countries deal with the heavy toll of the present conflict, it is very important to likewise not lose sight of the work required for long-lasting peace and prosperity.".
The current dispute in the Middle East has taken a major and immediate financial toll on nations in the surrounding area. The closure of the Strait of Hormuz and destruction of energy and public infrastructure have interfered with markets, increased financial volatility, and weakened the 2026 development outlook, according to the (MENAAP).
Leaving out Iran, overall growth in the area is expected to slow from 4.0% in 2025 to 1.8% for 2026. This projection stands 2.4 percentage points below the World Bank Group's January projections. The decline is concentrated in Gulf Cooperation Council economies and Iraq, which are greatly impacted by the dispute.
Future-Proofing GCC Portfolios for 2026 Shifts
Dangers are slanted to the disadvantage. In case of a prolonged conflict, the current impacts on the area will be compoundedthrough elevated energy and food rates, declining trade, tourist and remittances, increased fiscal pressures, and displacement. "The present crisis is a stark tip of the work ahead for the region: not only to weather shocks, however to restore more resilient economies with more powerful macroeconomic basics, innovate and improve governance, buy facilities, and enhance employment-creating sectors," said.
With peace and the ideal action, countries can build the organizations, abilities and competitive sectors that create opportunities for individuals." With this long-term vision in mind, the report takes a close appearance at the area's capacity for commercial policy government actions to increase strategic organization activity as a driver of financial development and job creation.
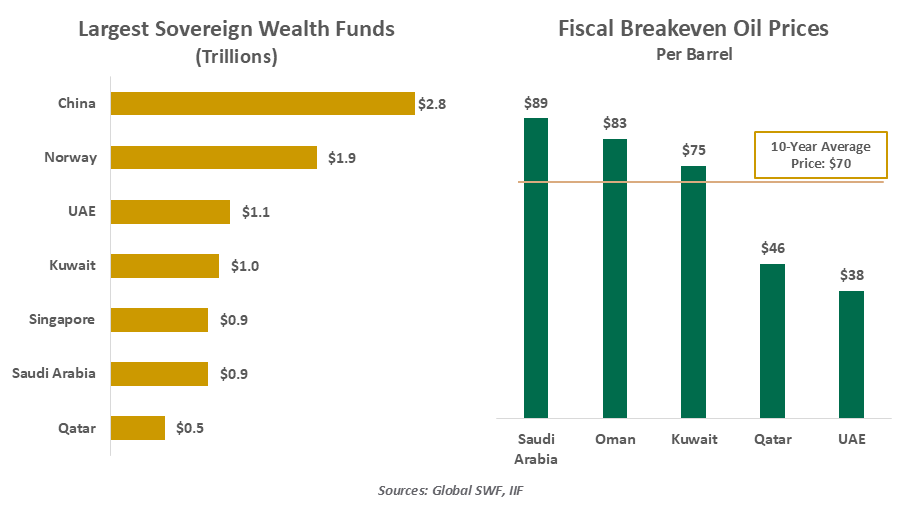
Governments in the area have actually embraced industrial policy at a high rate in the last years, typically through sovereign wealth funds and state-owned business, however the results have actually been blended. The report highlights the important need for strong institutions and cautious targeting of policies. "As nations deal with the heavy toll of today conflict, it is necessary to likewise not forget the work required for lasting peace and prosperity," stated.
Positioning Regional Portfolios against 2026 Shifts
The Gulf economies 2026, primarily the ones from the Gulf Cooperation Council (GCC) nations, are getting into 2026 with a fresh drive. The increase in oil production, the development of the Gulf non oil sectors, and the thorough structural reforms are the elements that will make the strong economic development possible.
Here are the major signs to observe along with the dangers it is better to understand before taking any action. The GCC financial outlook belongs to this shift, and signals continue to develop as the area positions for new momentum. Worldwide institutions give the green light to the Gulf's development in 2026.
This aligns with a wider GCC development forecast 2026 that reveals steady improvement. This recovery is an outcome of both the return of hydrocarbon activities and the advancement of Gulf non oil sectors. Tourism, logistics, manufacturing, and finance have been flourishing in the most populated and rich in oil countries of the GCC.
Privatization in Kuwait: Balancing State Interests and Market EfficiencyKey Foreign Capital Avenues in the GCC Market
Nevertheless, the growth is different in each case. Some forecasts recommend that the oil rate drop will cause the cooling down of the development rate. Likewise, if profits decrease, fiscal policy GCC in some nations will be under a heavy test, hence financiers must be particularly mindful to oil rate volatility GCC.

This is part of larger GCC diversification efforts that are starting to improve long-term expectations. In the United Arab Emirates, non-oil activities are approximated to be the main drivers of GDP growth, which would be around 5 to 5.6 percent in 2026. The sectors of tourist, trade, logistics, realty, and financial services continue to be the main engines of the country's economy, reflecting non oil sector growth in GCC nations 2026.

Latest Posts
Top Foreign Investment Trends within the Middle East Market
The 2026 Investment Landscape of the GCC
Optimizing Investment Strategies for Next-Gen GCC Economy