All Categories
Featured
Top Foreign Investment Trends within the Middle East Market
Optimizing Investment Strategies for Next-Gen GCC Economy

Creating Resilient Investment Structures with Arabian Securities
Table of Contents
All GCC nations deal with the obstacle of making sure future work for nationals while keeping reliance on foreign workers to fill particular roles, the urgency of this issue varies across nationwide contexts considering that GCC countries' demographics and concern areas diverge considerably. For countries that rely heavily on foreign labour, there is a danger that transition procedures will worsen poor working conditions and increase workers' vulnerability to exploitative practices.
Labour reforms in Qatar, for instance, abolishing the controversial labour sponsorship system (Kafala); and introducing a minimum wage, are significant examples of reform. Economic diversity and associated green shift plans create ample chances but likewise enhanced duties for business operating in the GCC area. Throughout this procedure, both federal governments and services have a responsibility to regard and advance worker well-being and account for future labour requirements through, for example, guaranteeing good working conditions and purchasing filling future skills spaces.
Whereas governments are required to provide robust regulative structures and enforcement mechanisms in line with worldwide standards, companies have a responsibility to respect worldwide recognised human rights and labour standards in line with the UN Guiding Principles on Organization and Human Rights. Companies can likewise use their leverage to guarantee that governments and partners enhance policies and accountability mechanisms, supplying an environment favorable to accountable company practices.
Anticipating this danger and building capability around how to fix this problem within the GCC context will be crucial to promoting responsible company in the region.
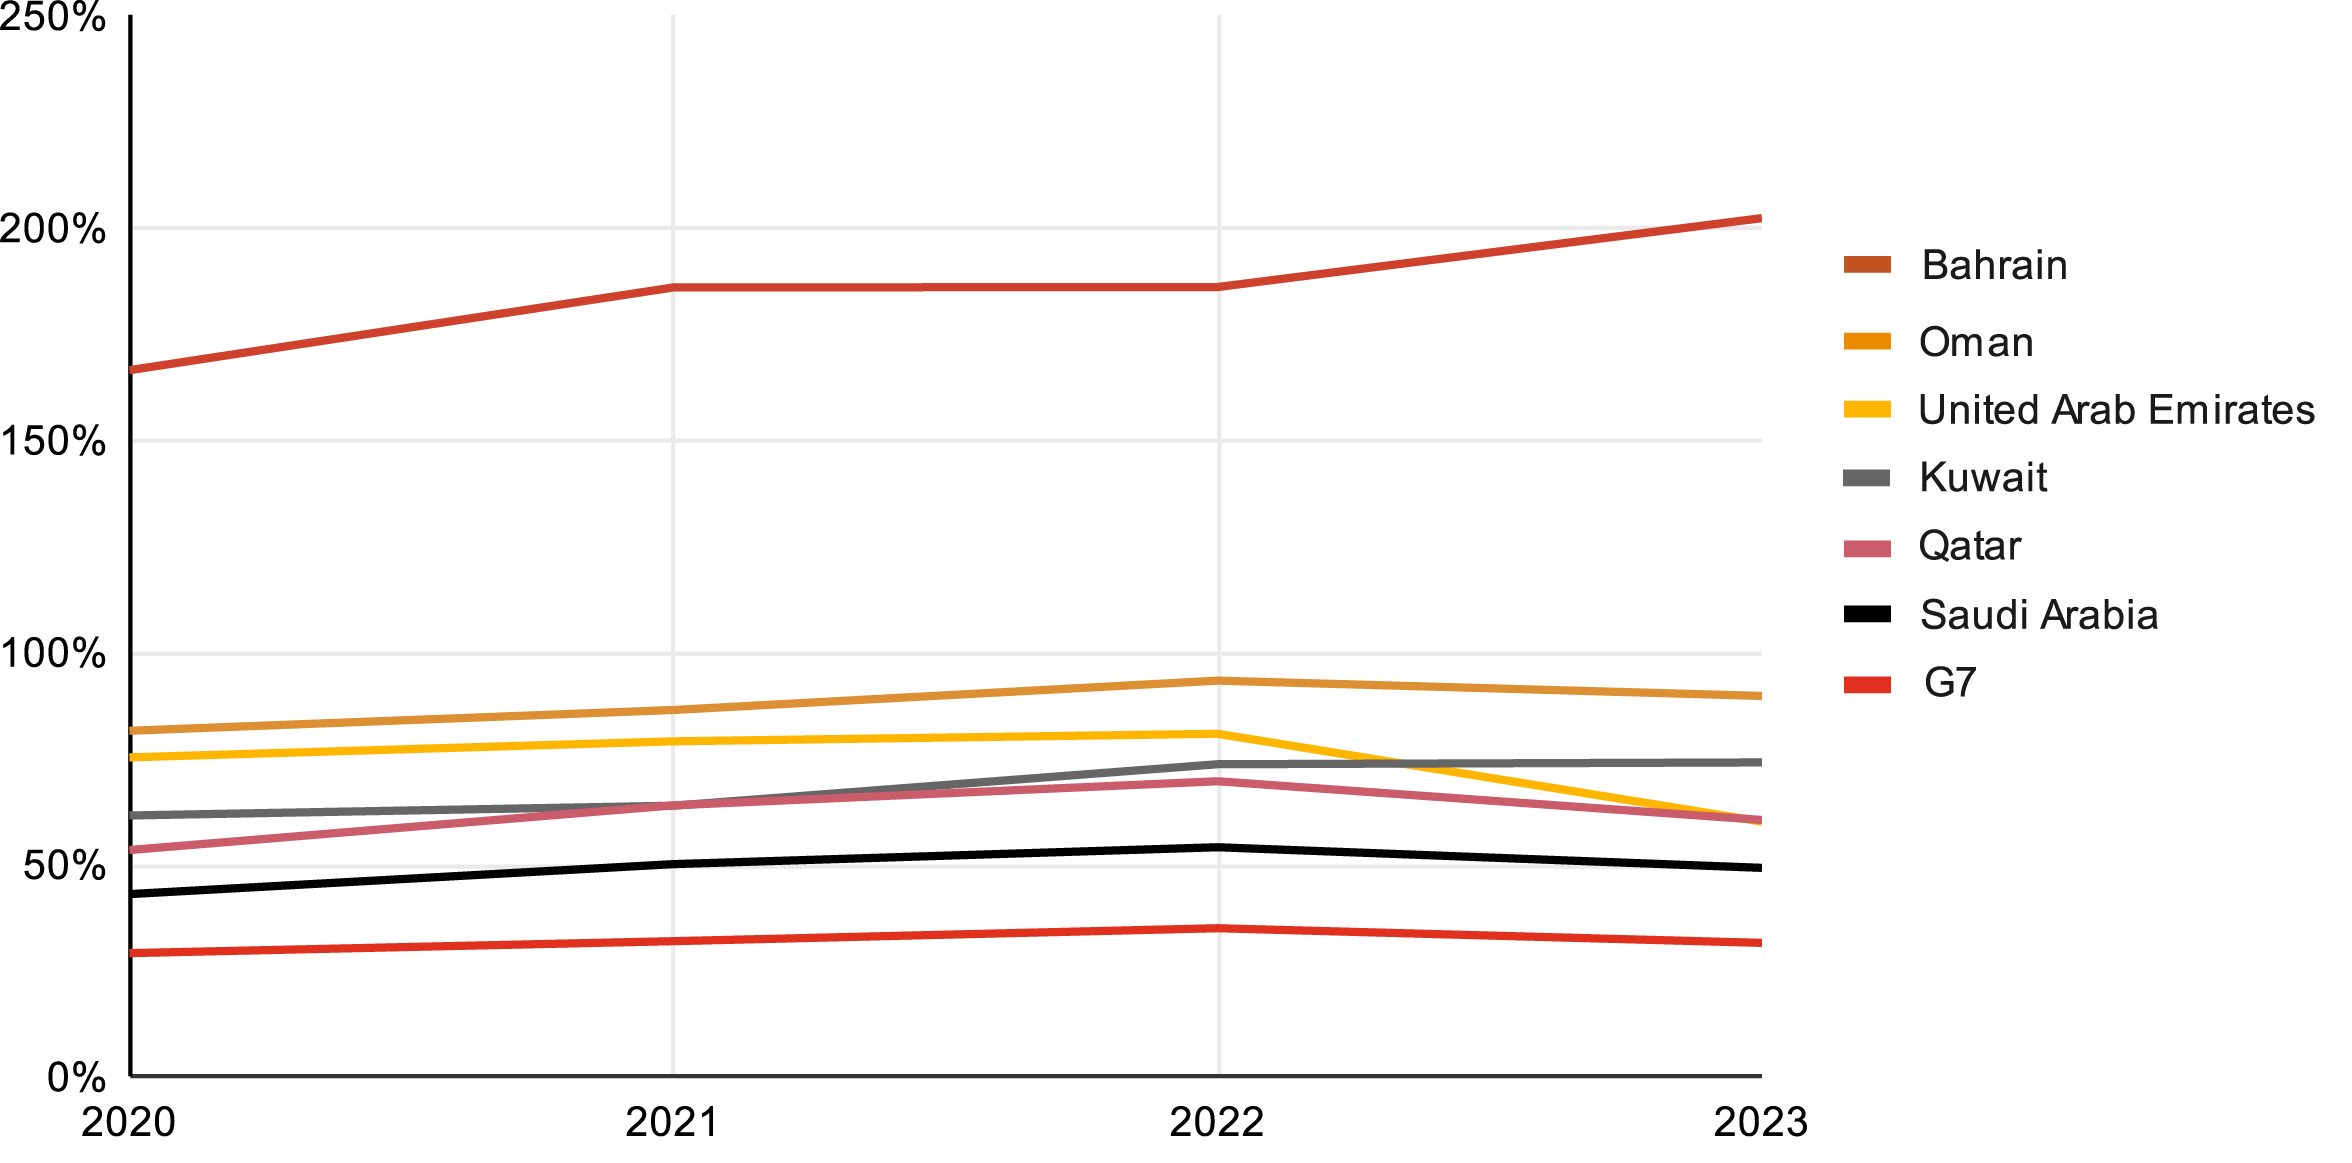
For decades, hydrocarbon incomes shaped the political economy of the Gulf Cooperation Council (GCC). In 2010, oil and gas represented more than 70% of federal government earnings across the majority of GCC states. Today, that figure is gradually declining not because oil has ended up being unimportant, however because diversification has moved from aspiration to execution, Invest-Gate reports.
Why Middle East Becoming Primary Investment Powerhouse?
The UAE's non oil sector broadened by more than 6% in 2023. This is not a short-term pivot. It is a structural improvement redefining financial impact and capital allotment in the area. The launch of in 2016 marked a turning point. Public Investment Fund (PIF) possessions have actually grown from approximately $150 billion in 2015 to over $700 billion in 2024, positioning it among the largest sovereign wealth funds worldwide.
Qatar has actually expanded LNG capability while accelerating financial investments in education, sports, and tourist following the 2022 World Cup. Oman and Bahrain have actually pursued financial debt consolidation and logistics driven diversity. These techniques function as financial operating systems coordinating policy, capital release, infrastructure advancement, and foreign financial investment tourist attraction. One of the most noticeable shifts is capital reallocation.
The UAE brought in more than $22 billion in FDI inflows in 2023, ranking among the leading international receivers. QatarEnergy dedicated over $30 billion to LNG expansion while parallel investments flowed into technology and sovereign portfolios abroad. Facilities, tourism, innovation, sustainable energy, and logistics are now soaking up capital when concentrated in upstream oil tasks.
Strategies for Capital Diversification in 2026 Global Markets
Diversification is not just financial it is geopolitical. Economic power is progressively determined by: Control over worldwide logistics passages Sovereign wealth fund impact in international markets Technological ecosystems Ability to attract global talent The UAE has positioned itself as a worldwide financial and logistics center. Saudi Arabia is leveraging scale and domestic demand to improve regional supply chains.
As non-oil sectors broaden, financial resilience improves. Break even oil costs have actually slowly decreased in some GCC states due to varied profits streams, consisting of VAT, business taxes, and financial investment income. Capital flows within the region are also altering. Riyadh is emerging as a local head office center following Saudi localization guidelines.
Future GCC Investment Shifts for 2026 Global MarketsAbu Dhabi sovereign entities are broadening strategic stakes worldwide. Doha is deepening collaborations across Asia and Europe. Personal equity, endeavor capital, and IPO activity have accelerated. Saudi Arabia led the area in IPO proceeds in 2023-2024, while the UAE continues to control in start-up financing and tech community maturity. This redistribution of economic gravity is gradually recalibrating local influence.
How Economic Diversification Boosts GCC Growth for 2026
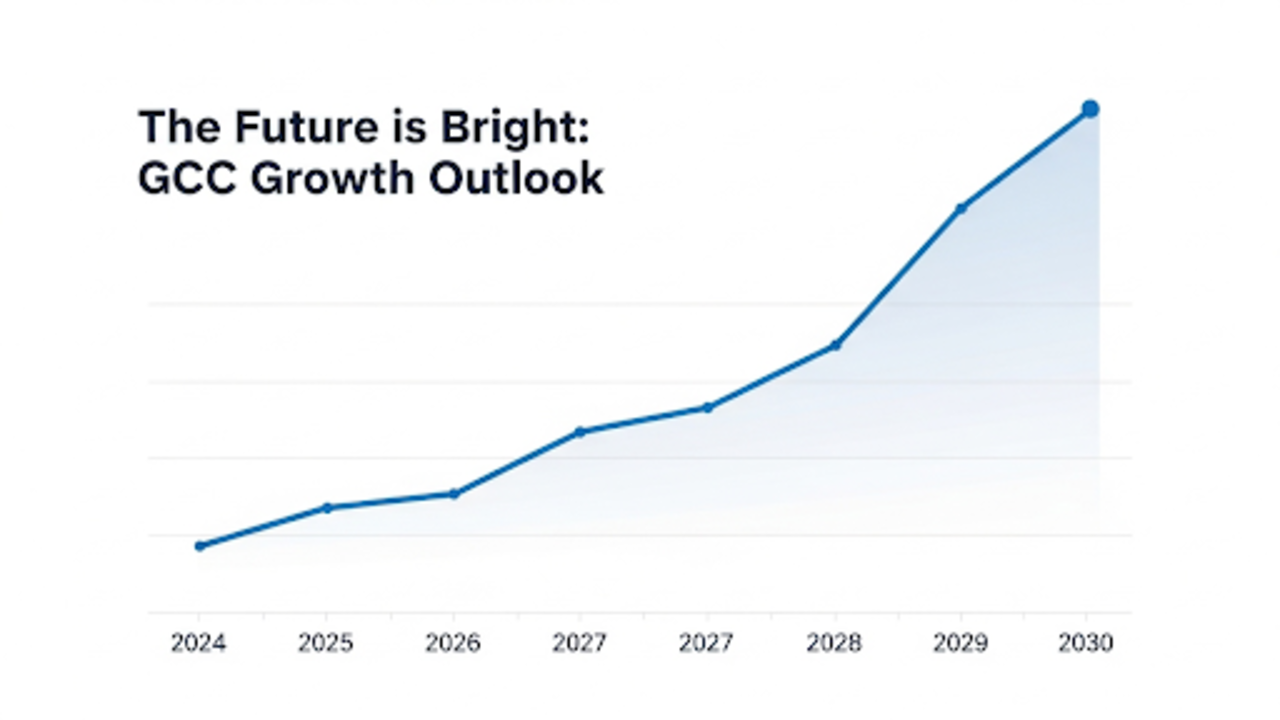
The GCC is stagnating "away" from oil it is moving beyond dependence on it. Hydrocarbons will remain central to fiscal strength and sovereign investment capability. However, the tactical shift lies in changing oil wealth into diversified financial power. By 2030, non-oil sectors are projected to contribute the bulk of incremental GDP growth throughout the region.
The improvement underway is redefining both regional hierarchy and worldwide capital integration.
Sweeping changes are concerning nations in the Gulf Cooperation Council (GCC). The United Arab Emirates (UAE) and the Kingdom of Saudi Arabia (KSA), long reliant on hydrocarbon exports, are charting a strong new course towards economic diversification. Regional production and production are at the forefront of the shift, together with blossoming sectors, including tourism, retail, and innovation.

Latest Posts
Top Foreign Investment Trends within the Middle East Market
The 2026 Investment Landscape of the GCC

Optimizing Investment Strategies for Next-Gen GCC Economy